

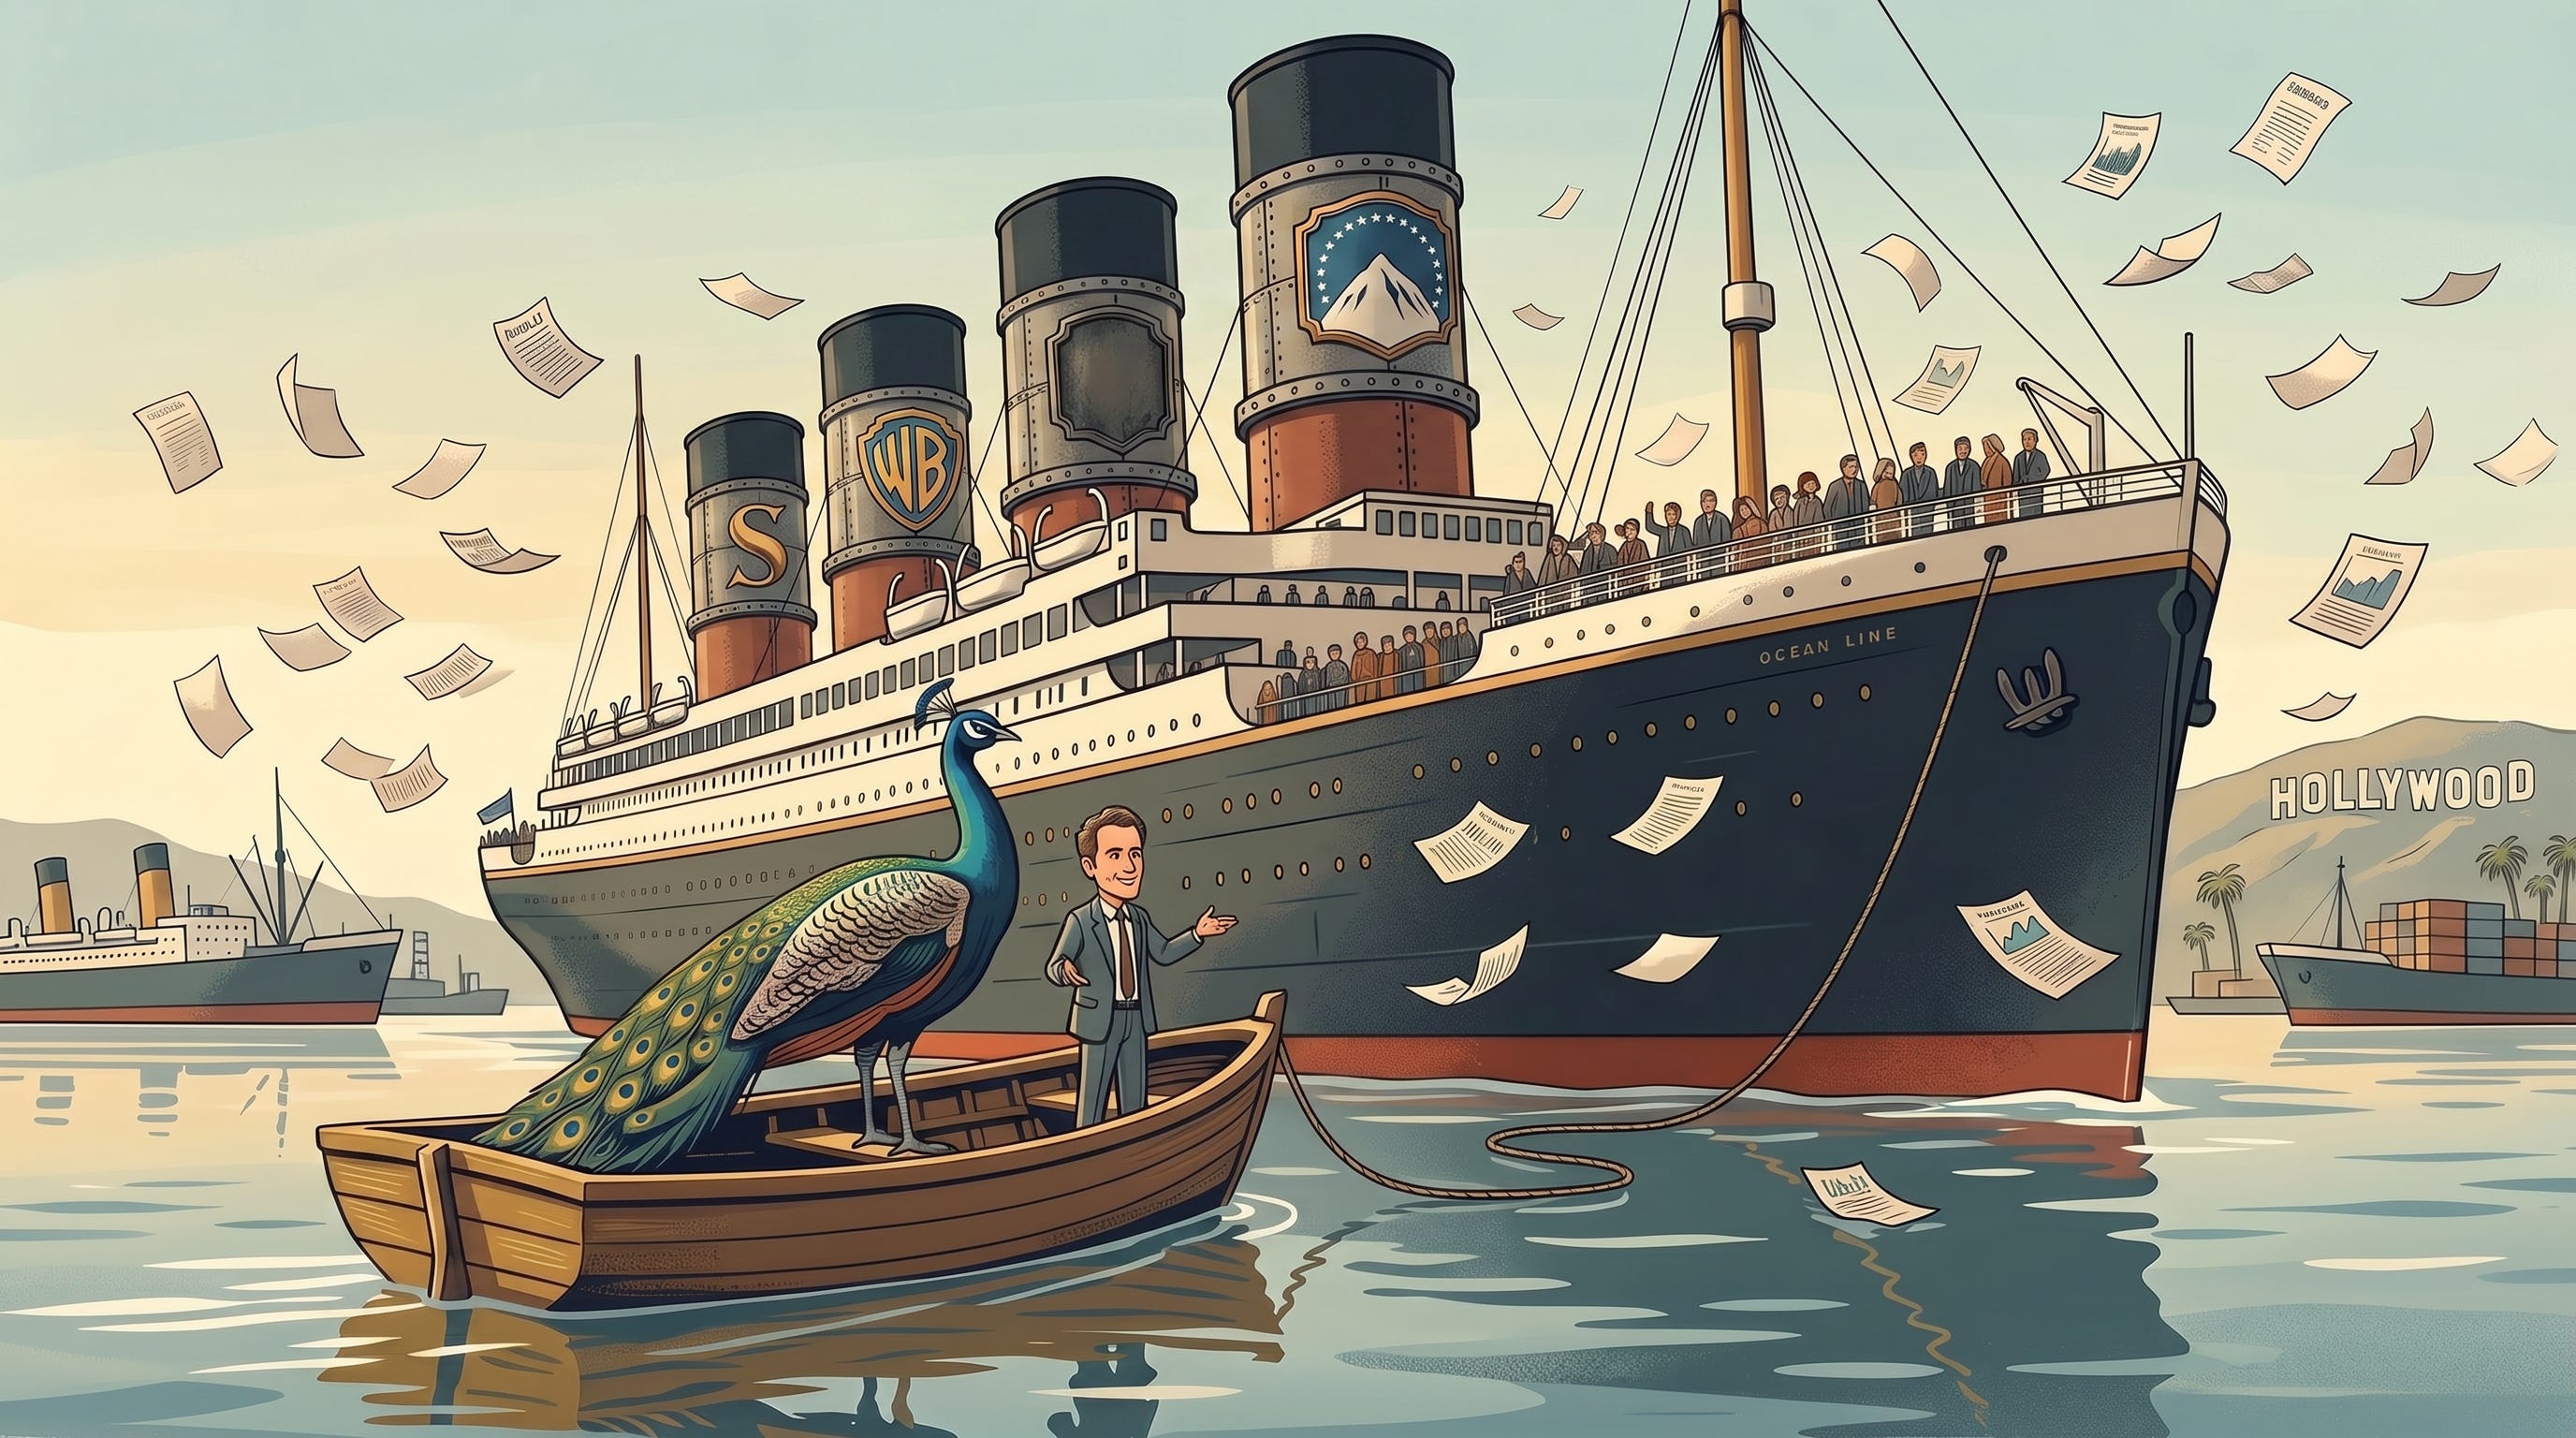
Since Comcast first announced its plans to spin off its NBCUniversal and Sky units into a new debt-laden standalone publicly traded company — which, for convenience, I’m just going to refer to as “NBCU” — one question has dominated the public conversation around the news:
So who’s going to buy NBCU?
And since day one, I’ve given the same answer to that question: don’t sleep on David Ellison.
Typically, my provocation elicits a response in the neighborhood of “No way. It’s unimaginable.”
To which I usually respond: have you been paying attention for the last decade or so? Because a lot of things that once seemed “unimaginable” — in this business, in this country, in this world — have proven to be very very real. And in this, the year of our lord 2026, the mere fact that something seems like it “couldn’t” or “shouldn’t” possibly happen just isn’t reason enough to conclude that it won’t.
Over the first two installments of this series, I’ve argued for why you shouldn’t underestimate the transformative impact of Comcast’s plans to spin off NBCU. I’ve pushed back on those who think it means the end of the bigger-is-better logic that has dominated the industry throughout the twenty-first century, and on those who dismiss the announced spinoff as “never going to happen.” But at the same time, I’ve joined the chorus of voices predicting that Comcast’s announcement will prove to be merely a prelude to a bigger process (and a bigger deal) that will truly define what the immediate future will look like — for NBCU, for its employees, and for the industry as a whole.
Today, I conclude my three-part series on the Comcast/NBCU split by taking a closer look at what that bigger process might look like. Is Comcast looking to expand NBCU or to expel it? What companies and individuals might be plotting their next big move right now? And is David Ellison taking over a third major studio really as unimaginable as it seems?
Is NBCU a Buyer or a Seller?
It’s a seller.1
That’s not to say that a standalone NBCU doesn’t have the wherewithal to be a buyer. But I don’t see any plausible acquisition targets that would materially improve its competitiveness as a standalone player.
Lionsgate? I actually have a soft spot in my heart for the perennially-for-sale Lionsgate, which I think deserves more credit than it gets for investing successfully in innovative but risky and unproven concepts and platforms (like AMC’s Mad Men and Netflix’s Orange Is the New Black2), or for nurturing a small but mighty list of surprisingly durable franchises (such as The Hunger Games, John Wick, Twilight, and Saw). But I don’t see how absorbing Lionsgate meaningfully changes NBCU’s competitive position, or makes it significantly more appealing as an acquisition target.
Sony? Unlike Lionsgate, Sony/Columbia seems substantial enough to meaningfully move the needle for NBCU both as an active competitor and an acquisition target. But Sony has demonstrated a consistently careful, cautious, and deliberate approach to high-level corporate dealmaking. As a buyer, it has largely focused on targets like Industrial Media and Alamo Drafthouse — big enough to meaningfully expand its capacities, but small enough to reliably ingest without choking. And while buyers love to speculate about it as a seller, I’m not aware of a single time that Sony Corporation in Japan has seriously entertained any such opportunity.
A24? A24, with its uniquely strong brand identity and cross-generational cool factor, would theoretically give NBCU something genuinely new and additive. But if its owners are looking for an opportunity to cash out, they may find that they’re a victim of their own success. A24’s private equity-driven $3.5 billion valuation will be hard to justify or sustain as part of a publicly traded enterprise. Even more importantly, it may well be impossible to convert A24 from a scrappy indie upstart to a subsidiary of a stodgy corporate behemoth without torching the brand credibility, distinctiveness, and goodwill that are the company’s greatest assets.3
Roku? Maybe if Fox hadn’t beaten them to it. No chance now.
If NBCU Is a Seller, Then Who’s the Buyer?
Saying that NBCU is ripe to be sold is easy. Identifying who will buy it is substantially harder. When Paramount and Warner Bros. went on the block in 2024 and 2025, respectively, there was a clear shortlist of credible buyer candidates for each. The outlook for NBCU is much murkier — many plausible options to entertain, many legitimate reasons to doubt each, and no clear frontrunner. None stands out as probable, in the sense of being more likely than not to happen. But some certainly seem more likely than others.
I’ve organized the candidates into three “tiers.” So let’s consider our candidates, from Tier 3 (least likely) to Tier 1 (most likely). Who tops the list?
Tier 3: Apple and Amazon
Why will it happen? Two numbers: 15.6 and 8.6. The first is the ratio of Apple’s market capitalization when the markets closed earlier today ($4.89 trillion) to that of Netflix, the most valuable “true” entertainment company, even if it refuses to acknowledge itself as such ($313 billion). The second is the ratio of Amazon’s current market capitalization ($2.69 trillion) to Netflix’s. If we instead compare Apple and Amazon’s market caps to that of Disney, the next most valuable entertainment power ($173 billion), those numbers become 28.3 and 15.5, respectively. In other words: Apple and Amazon can do pretty much anything they damn well please. If motivated, they cannot be outbid (except perhaps by each other). And Apple — whose streaming service boasts many of the kinds of high-quality originals that tend to attract subscribers, but almost none of the sticky franchises or beloved and rewatchable library titles that tend to retain them — could especially benefit from taking over the Universal content library.
Why won’t it happen? Just because Apple and Amazon could buy NBCU without breaking a (financial) sweat doesn’t mean they’d want to. That Universal content library is appealing, I’m sure. But I suspect both would be even more repelled by virtually every other part of NBCU, including the regulatorily intensive (and politically sensitive) broadcast TV business, the hospitality-adjacent theme parks business, and the highly unionized studio production facility business. Apple and Amazon are already managing significant public and governmental concern about artificial intelligence, and treading very lightly in a political environment that has grown increasingly hostile toward “Big Tech.”4 Neither is likely to make a move that could easily put a target on its back with a capricious presidential administration, skeptical and opportunistic legislators, and fired-up antitrust activists.
Tier 2: Netflix and the Usual Billionaire Suspects
Netflix
Why will it happen? After Apple and Amazon, Netflix is the biggest fish (with the deepest pockets) in the pond. Despite its success in most respects, Netflix has struggled to develop its own durable, multifaceted, and culture-defining franchises. Netflix already made a serious run at Warner Bros. Discovery; NBCU — with its robust theme parks business and particularly strong marketing operation — would arguably be an even better strategic fit. While Peacock may be a less shiny prize than HBO, it would be much easier to swallow culturally and operationally. And while buying NBCU may represent a less emotionally satisfying declaration of victory over “old Hollywood” than taking over HBO would have been, it would still make an unmistakable statement about who’s really in charge around here these days.
Why won’t it happen? Since dropping out of the bidding for WBD, Netflix has quietly worked to fan the flames of antitrust skepticism toward this kind of deal; reversing course now would require them to face a hostile regulatory and PR environment that is at least partially of their own making. Competition drove the price of Warner Bros. to unsustainable heights, enough to raise concerns about the debt burden a deal would require; if there is even one other serious bidder for NBCU, it’s likely to cost even more. The market already told Netflix how it felt about the idea of Netflix paying top dollar to buy a legacy studio, and it was not a fan: in the three months between Netflix’s announcement of its tentative deal to acquire Warner Bros.’ studio and streaming assets and its announcement that it would concede the deal to Paramount, the company’s stock lost over a quarter of its value. Worse still, although its share price briefly rebounded once Netflix walked away from the bidding for WBD ($2.8 billion richer for the failed effort), the recovery was short-lived: Netflix’s stock is back down to 25% below its price when the bidding began, and down around 40% from where the stock was trading this time last year. Ignoring that feedback to pursue NBCU could risk even greater damage to Netflix’s identity as a “technology company” rather than an “entertainment and media company,” and with it, even greater and more sustained harm to the company’s appeal to investors. Hard to imagine them playing with that kind of fire.
The Usual Billionaire Suspects
Why will it happen? If a studio is for sale, it’s a safe bet that somewhere out there, Byron Allen, Edgar Bronfman Jr., and Casey Wasserman are working the phones and trying to figure out if they can buy it for themselves. I’ve made this case before.
Why won’t it happen? For the same reason it hasn’t happened yet: these guys are at least as passionate and motivated as anyone on this list, but they’re not as well-resourced. They’re rich — insanely, incomprehensibly, problematically rich — but they’re not “single-handedly buy a major studio” rich. Any deal to acquire NBCU would require them to piece together a complex and fragile financing scheme with multiple backers. There’s no guarantee they could get a credible offer together at all; and even if they can, they’d be at a significant disadvantage relative to competitors with deeper pockets, more flexible financing options, and greater freedom to act decisively without having to muster support among multiple backers with their own agendas. Bronfman and Wasserman bring the family bona fides (and perhaps the faint memory of happier times for the business), but among the three, Allen appears to have the strongest track record to support this kind of deal — in the last year alone, he acquired a majority share of BuzzFeed and an 11% stake in Starz. But, as his targeting of BuzzFeed and Starz suggests, Allen’s greatest strength has always been efficiently squeezing every dime out of challenged or declining businesses, not in making costly strategic investments to compete among the industry’s major powers.5
Tier 1: Paramount-Skydance-WB-Redbird-Ellison
Why won’t it happen? Let’s reverse the order and start by talking about all the reasons why I might be freaking you out for no reason:
One of the things that helped elevate Paramount’s bid for Warner Bros. Discovery over Netflix’s was Ellison’s eagerness to acquire the entire company (as opposed to Netflix, which wanted to peel off only the company’s principal studio and streaming assets). That strategy is unquestionably off the table here — it’s safe to assume that the FCC — even this FCC — would regard joint ownership of CBS and NBC as a complete non-starter. Despite surprisingly strong and sustained resistance to the deal from both the creative community and state and foreign regulators, I still fully expect Paramount to overcome this week’s challenge from 12 state attorneys general (led by California’s Rob Bonta) and complete its acquisition of Warner Bros. Discovery. But the kind of resistance that an attempted roll-up of a third major studio would surely generate should give even the most bullish corporate consolidator pause.
The Ellison family’s vast personal fortune was instrumental to the successful financing of Ellison’s acquisitions of both Paramount and WBD. But much of that fortune comes from the family’s huge stake in Oracle, whose stock dropped by nearly 50% since this time last year, and by over 60% from its peak in September 2025. They’ve already pledged tens of billions of dollars as collateral for the loans being used to buy Warner Bros. — a guarantee made while Oracle’s stock was trading near its peak. Can they really have enough liquid and uncollateralized assets left to finance a third mega-deal in three years? And even if they could somehow finance a deal to acquire (most of) NBCU, would there be any money left to actually run it and invest in its further growth?
And yet…
Why will it happen?
Paramount’s core argument for why its acquisition of Warner Bros. should be approved is that the business’s future will be based on streaming, and even a combined Paramount+ and HBO Max is still sub-scale compared to the likes of Netflix, Amazon, and Apple. If that narrative wins the day, then it’s not a stretch to argue that adding Peacock — arguably the weakest of the major subscription streamers — still wouldn’t give the company monopolistic market power. To the contrary, it would just allow the company to close the remaining gap and compete as near-equals with its tech rivals.
The single biggest regulatory hurdle to a deal would be bringing NBC and CBS under one roof. That’s fine — they’d happily exclude the NBC broadcast network from the deal, just as Disney (owner of ABC) left the Fox broadcast network out of its deal to acquire most of Fox.
The next biggest regulatory hurdle would be on the theatrical production and distribution side. Much of the community’s resistance to the WarnerMount combination has focused on its impact on the market for feature film development, production, and distribution. But, consistent with its focus on direct-to-consumer streaming as the most significant and relevant market, Paramount could partially defuse that resistance (and its antitrust risk with foreign as well as domestic regulators) by also leaving the Universal Pictures film studio out of the deal. This would require some complex rights management between the divorcing film and TV units. But Paramount already knows a thing or two about making that work — once-shared operational and intellectual property assets were divided between CBS (for TV) and Viacom (for features) when the companies split in 2005.
Another node of controversy around the Paramount/WBD deal has been the prospect of bringing CBS News and CNN under one roof, and the implications of that combination not just for the American news business, but for American democracy. But those concerns won’t be in play for a deal to add NBCU, since MSNBC — sorry, MS NOW — has already been spun off into Versant.
Comcast has announced its intention to maintain a stake in the spun-off standalone NBCU. Assuming the Roberts family (which controls Comcast) would be similarly interested in keeping a significant long-term position in a combined Paramount/WB/Universal, that opens the door to a more stock-heavy, less cash-and-debt-intensive structure than the brute-force $110 billion all-cash fight we just watched.
Now: does it still sound so “unimaginable” to you? Because if you’re forcing me to bet, my money is on the guy who, one way or another, always seems to get what he wants.
Could NBCU “Go It Alone” Without Fully Going It Alone?
Again, it’s not a fait accompli that NBCU will be sold, and I believe Comcast is fully prepared to go through with its spinoff plans as announced (assuming a more appealing option doesn’t present itself first).
But a standalone NBCU — whether as it has been proposed or under new owner-management (see “The Usual Billionaire Suspects” above) — doesn’t mean an NBCU that must simply do its best to carry on with business-as-usual. And while I doubt Netflix’s appetite to buy NBCU outright (for the reasons described above), there is a way that it could, as the old actually-pretty-disturbing-and-misogynistic-if-you-think-about-it saying suggests, “get the milk for free without having to buy the cow.”
An independent NBCU could very reasonably conclude that Peacock is too expensive, and too far behind its competitors, to justify its place at the strategic heart of the company’s future business. But rather than writing it off altogether, NBCU could enter into a joint venture, or some kind of exclusive licensing arrangement, to turn Peacock into an NBCU-branded and programmed tile on the Netflix service. NBCU would retain a consumer-facing brand while saving billions by essentially outsourcing the effort and expense of operating the service.
There’s plenty of precedent for this sort of thing. While Disney continues to offer Hulu as a standalone service, it is in the midst of a long-term process of essentially converting Hulu into a tile on Disney+ — a process that I suspect would already be complete if not for the company’s Hulu + Live TV virtual MVPD offering. It wouldn’t even be novel for Netflix, whose French service already offers dedicated tiles featuring local live channels with companion on-demand options. And it would fit in nicely with current trends toward multi-channel streaming services and bundled subscriptions combining services from competing providers.
This strikes me as the best of the plausible outcomes — not just the least traumatic for the employees of NBCU (or for the town as a whole), but the healthiest for the overall competitive landscape of the industry. It offers NBCU the opportunity to preserve as much value as possible from what it has built, to bow out gracefully from the losing game of competing head-on with the tech companies in direct-to-consumer streaming, and to start charting a sustainable path forward for itself as an independent mid-major power.
Of course, in this, the year of our lord 2026, the mere fact that something seems like it really “should” happen just isn’t reason enough to conclude that it will. But we can hope.
This post is always free, one of a handful that will never go behind the paywall. Share it with anyone.
I was very tempted to drop the mic there and move on.
Debuting in 2007, Mad Men put AMC on the map as a purveyor of original content. And while the show didn’t exactly invent the “basic cable premium drama” fronted by a brooding and morally ambiguous antihero — a distinction that probably belongs to FX’s The Shield — it kicked off a decade-long golden age for the genre that quickly yielded all-timers like Breaking Bad, Justified, The Americans, The Walking Dead, and Mr. Robot and laid the foundation for the streaming originals era. 2013’s Orange Is the New Black was Netflix’s third-ever original drama (excluding European co-production/acquisition Lilyhammer), and arguably trails only House of Cards in its influence on both the creative sensibility of and studio dealmaking for streaming originals. It remains to this day Netflix’s second-longest-running original, trailing only Grace and Frankie (by just three episodes over seven seasons).
Assuming those even survive A24’s highly controversial new “research partnership” with Google AI’s DeepMind.
Amazon is also still smarting from its acquisition of MGM, for which it spent $8.5 billion to buy an impossibly complex and encumbered library, a third-tier linear network, and ownership of the James Bond franchise (which required an extra $1 billion to the Broccoli family for Amazon to actually be able to do anything with it).
When Paramount was for sale, the conventional wisdom was that an acquirer would likely want to pull a Versant — that is, to spin off the company’s cash-generative but declining linear cable assets, and use the proceeds to invest in the core studio/streaming business. Allen pursued the company with an inverted plan — to buy the whole megillah, quickly sell off the more “appealing” studio and streaming businesses to effectively pay off the whole transaction immediately, and to hold onto and wring every last cent from the remaining pupu platter of unsexy assets.
Wild card and totally fantasy football corporate M&A edition, but hear me out (pure personal speculations):
- NBCU spins off local stations and RSNs to the soon-to-be-merged Nexstar/Tegna
- Rationalizes duplicative international channels and converts sports-light channels (e.g., DreamWorks Channel, 13eme Rue) to FAST or exit with local ad-sales operations either integrated or outsourced in these markets
- Enters into a joint streaming venture with Apple TV and powers Apple's ad sales
- Builds gaming partnerships with Nintendo
- Doubles down on experiences and start its cruise/ vacation clubs/ timeshare partnerships with Royal Caribbean to develop land and sea Universal vacation packages